Veterans Day 2026: How VA Home Loans Help Fredericksburg-Area Buyers Get In Sooner
On Veterans Day, it's worth looking at one of the most valuable benefits that military service earns: the VA home loan. A new Realtor.com analysis published this week puts a number on it, finding that a zero-down VA loan can put an eligible buyer into a home roughly four years sooner than saving for a conventional down payment. For the Fredericksburg region, home to many active-duty, Guard, Reserve and retired military families connected to Marine Corps Base Quantico, Naval Support Facility Dahlgren and the wider Washington defense community, that's more than a national headline.
Here's what the latest research and policy news say, and how it applies if you're buying or selling in Fredericksburg, Stafford, Spotsylvania, King George or Caroline.
What the new VA loan research found
Realtor.com's analysis, published Nov. 10, compared VA purchase loans with conforming loans over the past year:
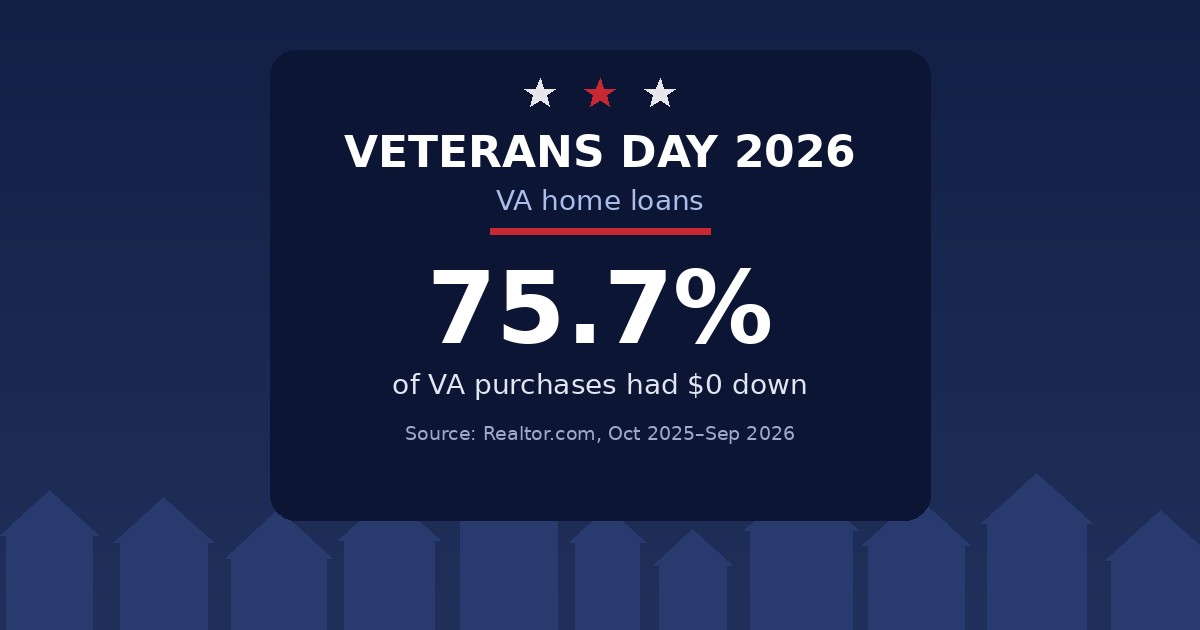
- 75.7% of VA-financed purchases had no down payment at all, and 86.1% had less than 10% down. Only 41.1% of conforming-loan purchases came in under 10% down.
- From October 2025 through September 2026, 30-year fixed VA purchase loans averaged 5.81%, versus 6.22% for conforming loans.
- With 10% down on a median-priced home, a VA borrower would save about $261 a month, or more than $3,100 a year, compared with a similar conforming borrower.
- A 0%-down VA loan costs about $20 more per month than a conforming loan with 10% down, but saves $41,925 upfront, which is where the roughly four-year head start comes from.
The same report noted that just 3 in 10 veterans know they can buy with zero down, according to a Veterans United survey, and that many don't realize the benefit can be used more than once, as long as they meet lending and occupancy requirements.
Why it matters in today's rate environment
The timing is notable. Mortgage rates jumped Tuesday after a hotter-than-expected October inflation report. Mortgage News Daily's index showed the average top-tier 30-year fixed rate up 0.12 point to 7.30%, the largest one-day rise in more than a month. Its 30-year VA average rose to 6.90% on the same day. Bond markets are closed for Veterans Day, so the next meaningful rate update comes later this week.
Buyers who use VA financing are already responding to any window of relief. In the Mortgage Bankers Association's latest weekly survey, reported by Realtor.com, the VA share of all mortgage applications rose to 12% from 11.2% the week before.
When rates sit above 7%, every advantage matters. A lower average rate, no monthly mortgage insurance and the ability to keep savings in the bank for moving costs, repairs or reserves can make the difference between buying this year and waiting.
New help for veterans who fall behind
VA loan news this week isn't only about buying. The VA's Partial Claim Program, which helps veterans who have fallen behind on their mortgage payments, took effect June 15, and mortgage servicers have until Nov. 28 to finish implementing it, according to The Center Square. Under the program, VA reimburses servicers for missed payments and certain fees to bring the loan current. The veteran repays that amount, without interest, when they sell, refinance, pay off the mortgage or reach the end of the loan term. Borrowers must first complete a three-month trial payment plan.
A Government Accountability Office report released Tuesday found that VA doesn't yet have a comprehensive plan to evaluate the program and doesn't intend to begin analyzing outcomes until December 2027. The program is set to expire in July 2030 unless Congress extends it.
If you or someone you know is behind on a VA-backed mortgage, the first call should be to your loan servicer to ask about available options.
What VA loans don't do
A VA loan isn't free money. Most borrowers pay a one-time VA funding fee, although VA says the fee is waived for veterans receiving compensation for a service-connected disability, eligible surviving spouses receiving Dependency and Indemnity Compensation, and certain other borrowers. You'll still have closing costs, property taxes, homeowners insurance and maintenance to plan for. As VA Deputy Secretary Paul Lawrence put it in a Nov. 7 VA News interview about the agency's new awareness effort with the National Association of Realtors: "Zero down payment doesn't mean zero responsibility."
What this means for local buyers
- Check your eligibility early. Get your Certificate of Eligibility and talk to a lender experienced with VA loans before you start touring homes.
- Don't assume you've used it up. If you've used a VA loan before, ask a lender whether you have remaining entitlement or can restore it.
- Use the savings wisely. Zero down can let you keep cash for inspections, moving costs and an emergency fund.
- Plan for PCS timing. Frequent moves are one reason military homeownership lags. Think through whether a home could work as a rental if orders change, and confirm occupancy rules with your lender.
What this means for local sellers
VA News noted that some veterans still believe VA offers are slower or less attractive to sellers, and that much of that perception is outdated. With a large military buyer pool in our region, sellers who welcome VA financing and prepare for a standard appraisal and inspection can widen their audience. Simple steps, like addressing obvious safety or repair issues before listing, can help any financed sale close smoothly.
Thinking about your next move?
To every veteran and military family in the Fredericksburg area: thank you for your service. If you're weighing a purchase, a PCS move or a sale, I'm happy to walk you through how VA financing fits into today's market and connect you with the right local resources. Reach out to me, Alex Wilson, at Go Wilson Properties anytime.
Sources: Realtor.com VA loan analysis (Nov. 10, 2026); Mortgage News Daily (Nov. 10, 2026); Realtor.com on the MBA weekly survey (Nov. 11, 2026); The Center Square on the GAO report (Nov. 10, 2026); VA News (Nov. 7, 2026); VA.gov funding fee guidance. This article is general information, not lending or legal advice; eligibility and terms depend on each borrower and lender. Featured image: original graphic by Go Wilson Properties.